Cover forthe people whodepend on you.
Private medical insurance, income protection and life or critical illness cover — introduced and arranged around your own circumstances, whatever "unable to work" would actually mean for the people who count on you.
Built for mums
Or ring 01656 856120 (Option 3)
Arranged through insurers including
Access to private diagnosis and treatment
Private medical insurance gives access to private diagnosis and treatment for eligible acute conditions, subject to the policy's terms and exclusions. The value is usually speed — an MRI in days rather than months, a specialist appointment that doesn't sit on a waiting list — so a wait doesn't cost you weeks of worry.
Which level of cover, if any, suits your circumstances is a conversation — we introduce and arrange, we don't advise on this website, and nothing here is a quotation or a comparison of premiums.
- Options for individuals and for the whole family on one policy.
- Cover can include physiotherapy and outpatient diagnostics, depending on the policy.
- Introduced through insurers on our panel — terms, exclusions and eligibility are theirs, not ours.
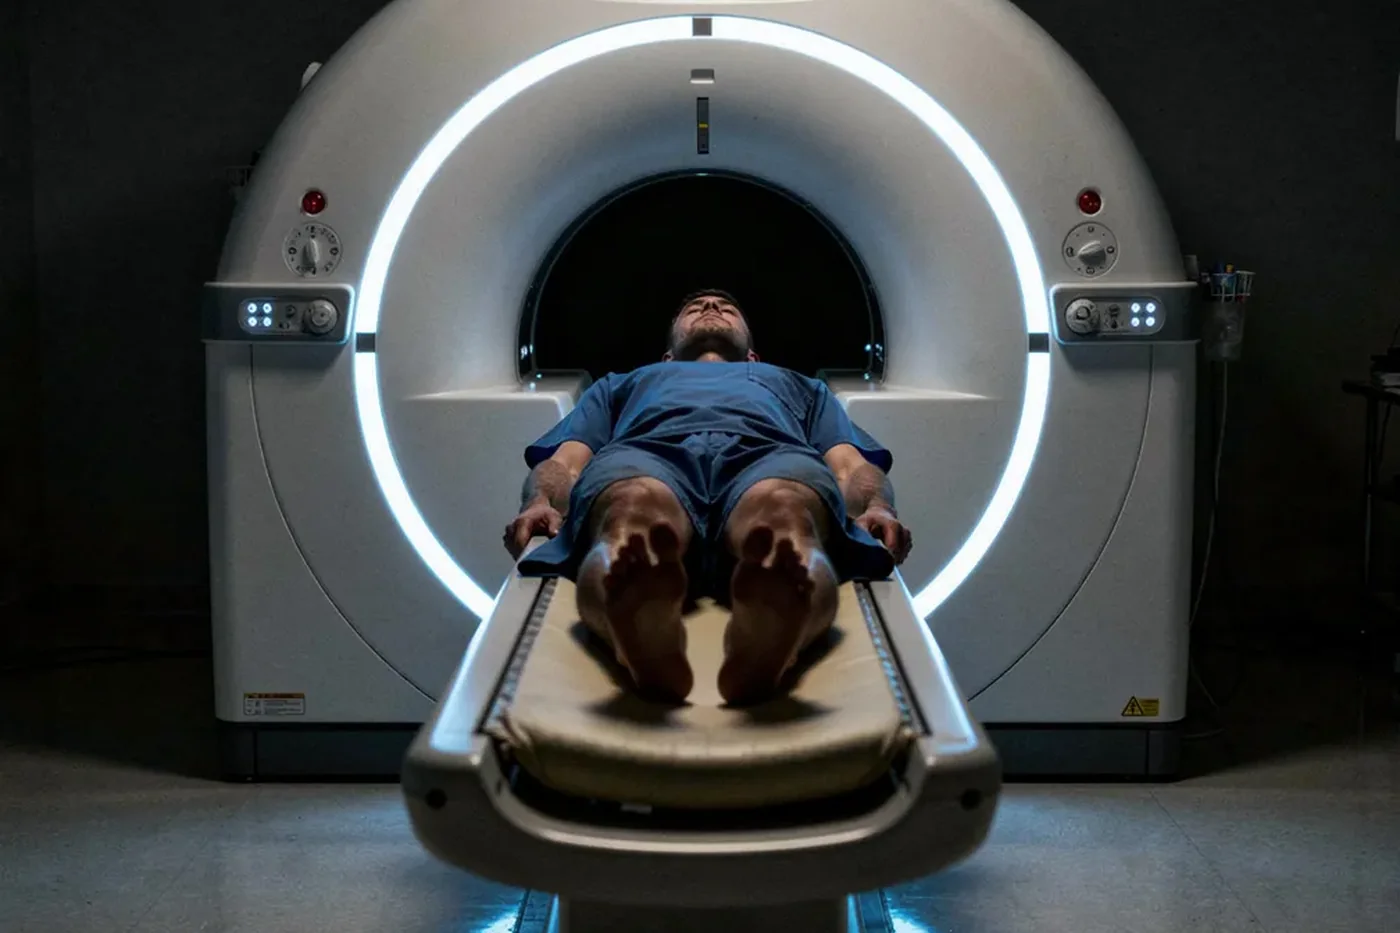
Waiting three months for a scan is three months of worrying. Worth a conversation.
On our panel for this cover
A monthly benefit while you can't earn
Illness or injury doesn't check your job title first. Income protection pays a monthly benefit while you're unable to work — arranged around your salary or your own income, not a one-size policy.
Work out the gap first — it's your own two numbers, and it takes ten seconds.
Salary, self-employed profit — anything that stops when you do.
£450 × 12 weeks = £5,400
Around 50–60% of your earnings — the usual shape of an income protection policy.
What these figures are The first is arithmetic on the two numbers you typed: your weekly playing income multiplied by the weeks you selected. The second shows the proportion of earnings this kind of cover is generally built to replace, applied to your own figure. Neither is a quote, an estimate, or a statement of what any policy would pay you. What you'd actually be offered depends on the insurer, your job, your health and the waiting period you choose — that's a conversation, not a sum.
If the number above looked uncomfortable, that's the conversation worth having.
On our panel for this cover
A lump sum when it matters most
Life cover pays a lump sum on death within the term chosen. Critical illness cover pays a lump sum on diagnosis of a condition specified in the policy, again within the term chosen. The two are often arranged together, and the right term and level depend on your circumstances — mortgage, family, income.
We introduce and arrange this cover; we don't advise on this website, and nothing here is a quotation or a recommendation.
- Life cover and critical illness cover, arranged separately or together.
- Term lengths matched to your circumstances, not a default number.
- Introduced through insurers on our panel — terms, exclusions and eligibility are theirs, not ours.
Most people set this up once and never think about it again. Fifteen minutes now.
On our panel for this cover